Casurance

Call: 1-888-254-0089  ·  Mon–Fri 9 am–5 pm PST  ·  Licensed in CA, TX, NV & all 50 states  ·  info@casurance.com

Commercial property building with comprehensive insurance coverage

Commercial Property Insurance: Real Claims Examples

Quick Answer

Real-world Commercial Property Insurance claim scenarios showing what was covered, how much was paid, and lessons for business owners.

Comprehensive FAQ, cost guide, and claims examples for commercial property insurance — coverage for business buildings, equipment, and inventory.

Coverage Summary

Commercial property insurance covers business buildings, equipment, inventory, and fixtures from fire, theft, vandalism, and weather damage.

Fire in Restaurant Kitchen

Industry: Restaurant

A grease fire caused significant damage to a restaurant kitchen and dining area.

Claim amount: $150,000

Outcome: Property insurance covered kitchen equipment replacement, structural repairs, and dining area restoration.

Lesson: Regular hood cleaning and fire suppression maintenance reduce kitchen fire risk.
Learn from the loss. Strengthen your next policy.

Explore the claim examples, identify the questions they raise, and ask Casurance to review your future coverage needs.

Modern mixed-use commercial building with retail frontage and offices

Create a clear record of affected property

Organized warehouse inventory and business equipment
  • Photograph: affected rooms, equipment and inventory when safe.
  • Identify: item ownership and where it was located.
  • Support: collect receipts and pre-loss records.

When it is safe to do so, photograph the affected rooms, equipment, inventory and building components. Keep a list of damaged items and note their location. Gather available purchase records, maintenance documents and pre-loss photographs. Separate your property from tenant-owned or customer-owned items so the adjuster can review ownership.

Protect the property and keep receipts

Building inspector reviewing rooftop mechanical equipment
  • Safety first: follow emergency-service instructions.
  • Temporary measures: document work to prevent more damage.
  • Keep receipts: discuss permanent repairs with the insurer.

Follow emergency-service instructions and avoid unsafe areas. Arrange reasonable temporary measures to prevent further damage when safe, and keep invoices and a record of the work. Discuss permanent repairs and disposal of damaged items with the insurer so important evidence is not lost before inspection.

Track the effect on operations and rent

Neighborhood retail storefront ready to welcome customers
  • Dates: log closures, restricted access and reopening.
  • Income: organize sales reports, payroll and rent rolls.
  • Extra costs: retain receipts and explain the expense.

Record closure dates, restricted access, interrupted tenant operations and the timeline for reopening. Keep sales reports, rent rolls, payroll records and additional-expense receipts organized by period. These records can help an adjuster assess a requested business income or rental income claim, subject to the coverage purchased.

Keep the claim file in one place

Property photographs, plans and documents organized for review
  • Report the loss using your carrier's claims instructions.
  • Keep the claim number and adjuster's contact details together.
  • Date your photographs, correspondence and follow-up notes.

Report the loss promptly using the carrier's claims instructions. Save the claim number, adjuster's contact details, policy documents, photographs and correspondence together. Maintain a dated log of calls, inspections, estimates and requested documents. Ask for clarification when a request or coverage explanation is unclear.

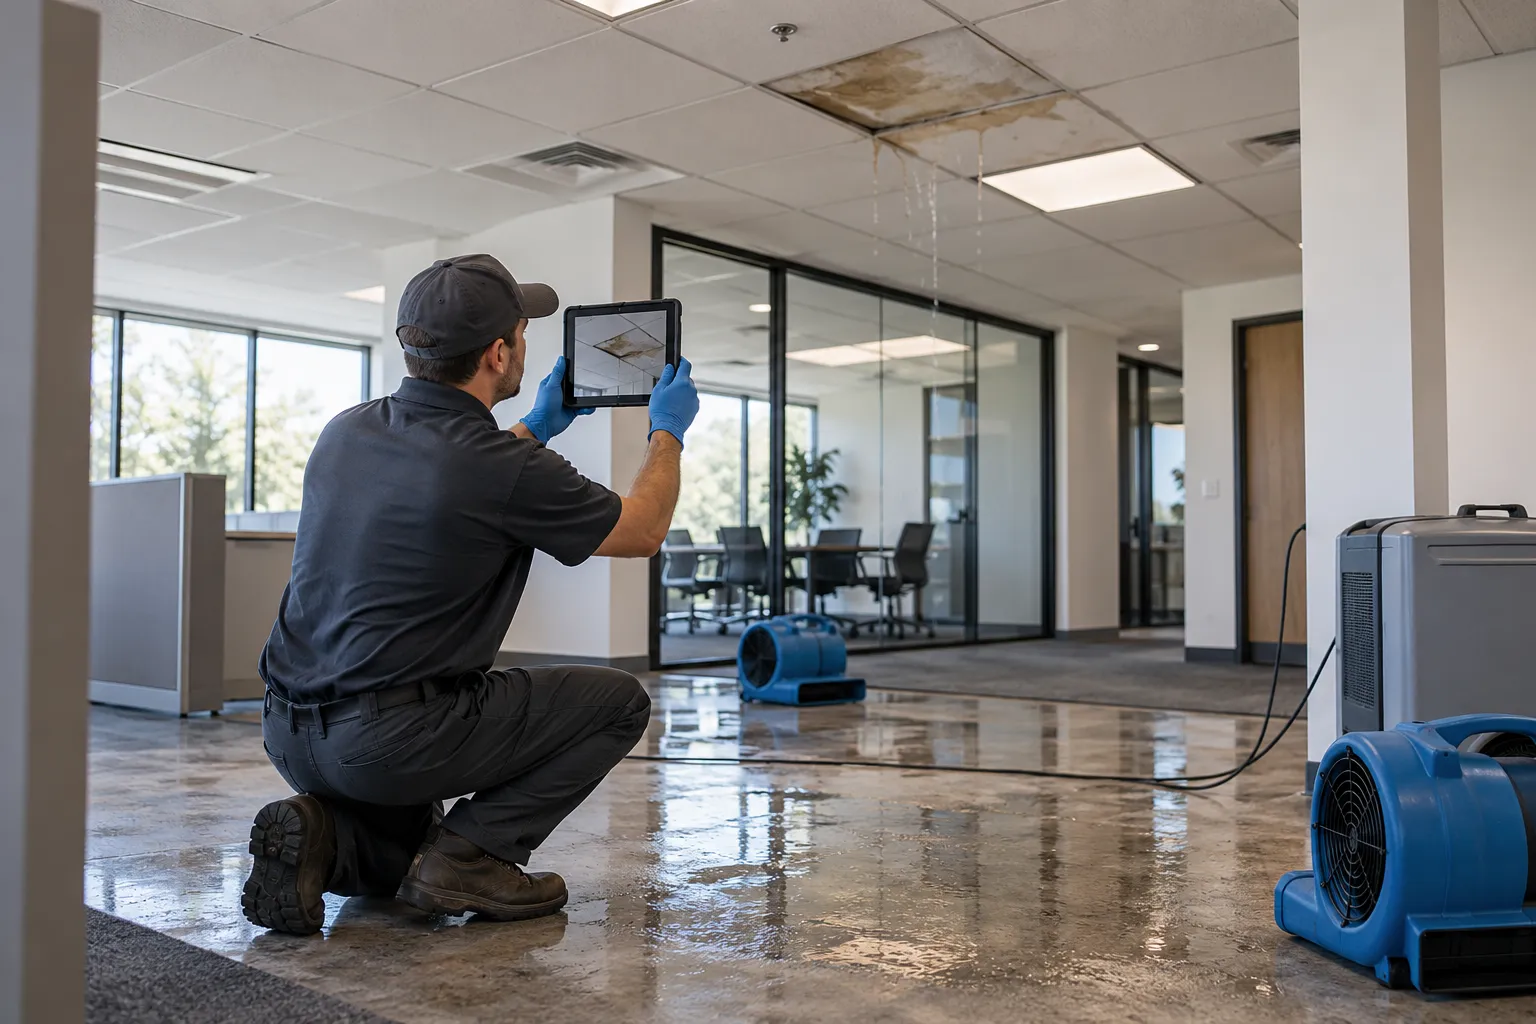
Document the source of water damage

Restoration professional documenting water damage in a commercial office
  • Source: record where water entered and when it was discovered.
  • Evidence: keep plumber or restoration reports.
  • Coverage: let the insurer review the cause and policy terms.

Describe when the problem was discovered, where water entered and what was observed. Preserve plumber or restoration reports and photographs where available. Do not assume every water event is treated alike. The insurer must review the cause, applicable endorsements and exclusions before determining how the policy responds.

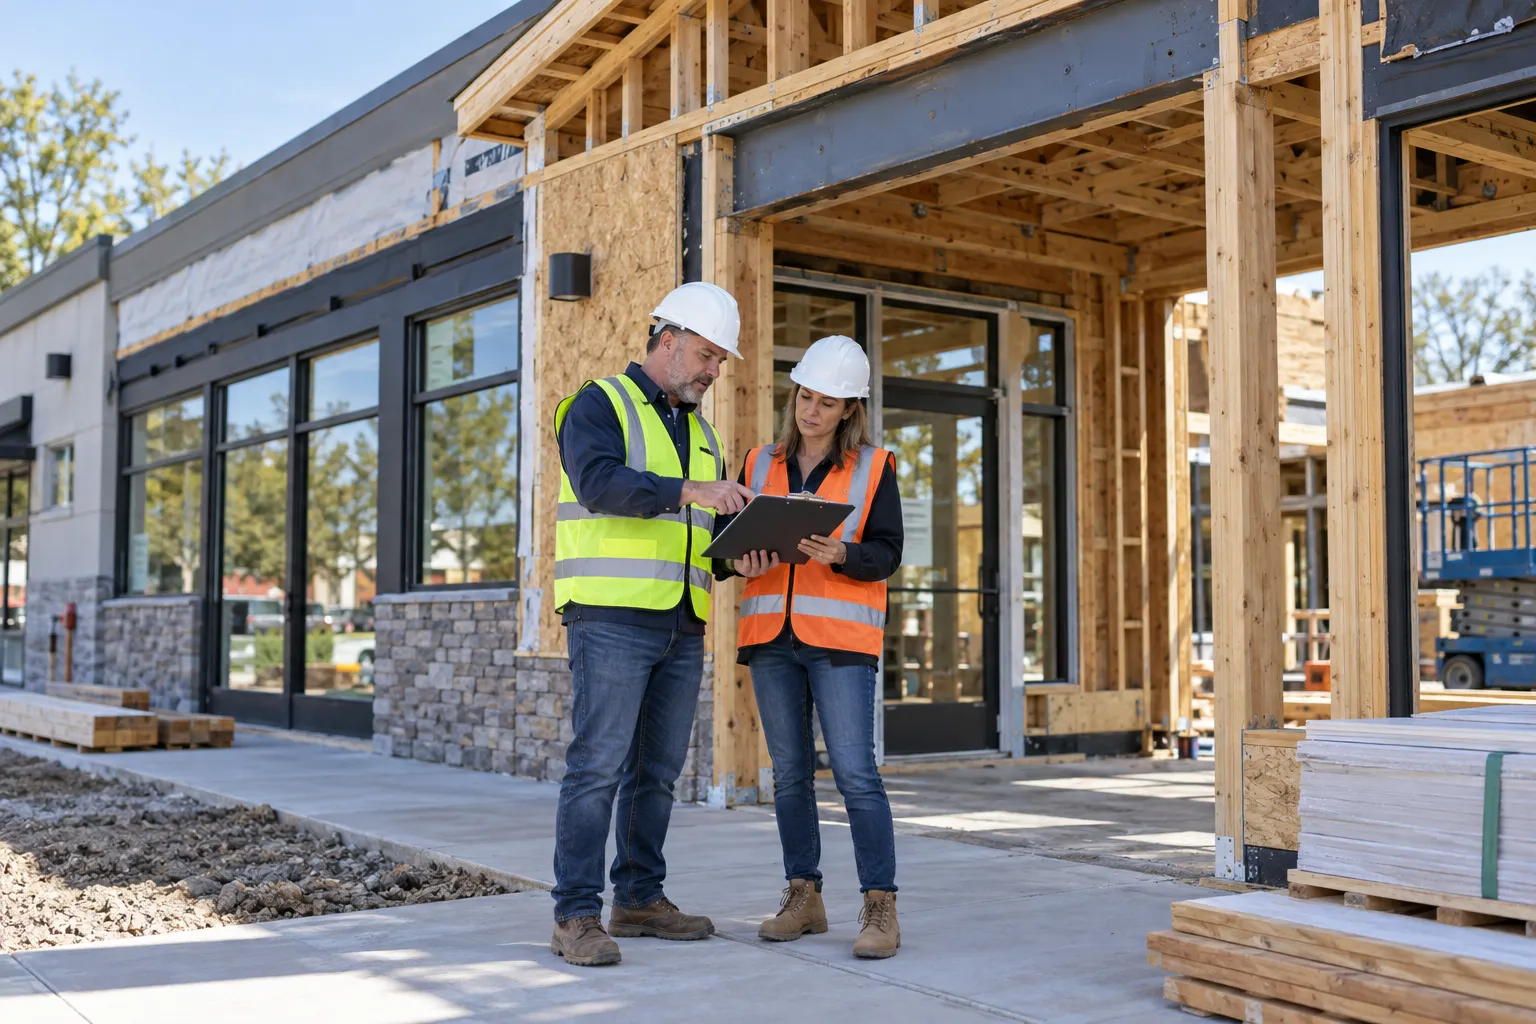
Coordinate estimates, repairs and the recovery timeline

Professionals reviewing a commercial building restoration project
  • Scope: share contractor estimates with the adjuster.
  • Progress: record permits, change orders and work completed.
  • Settlement: ask about remaining documents and deductible treatment.

Share contractor estimates with the adjuster and identify differences in scope, materials or repair methods. Keep records of permit requirements, change orders and work completed. Ask which costs and documentation remain outstanding, and request an explanation of how the deductible and settlement provisions apply to the claim.

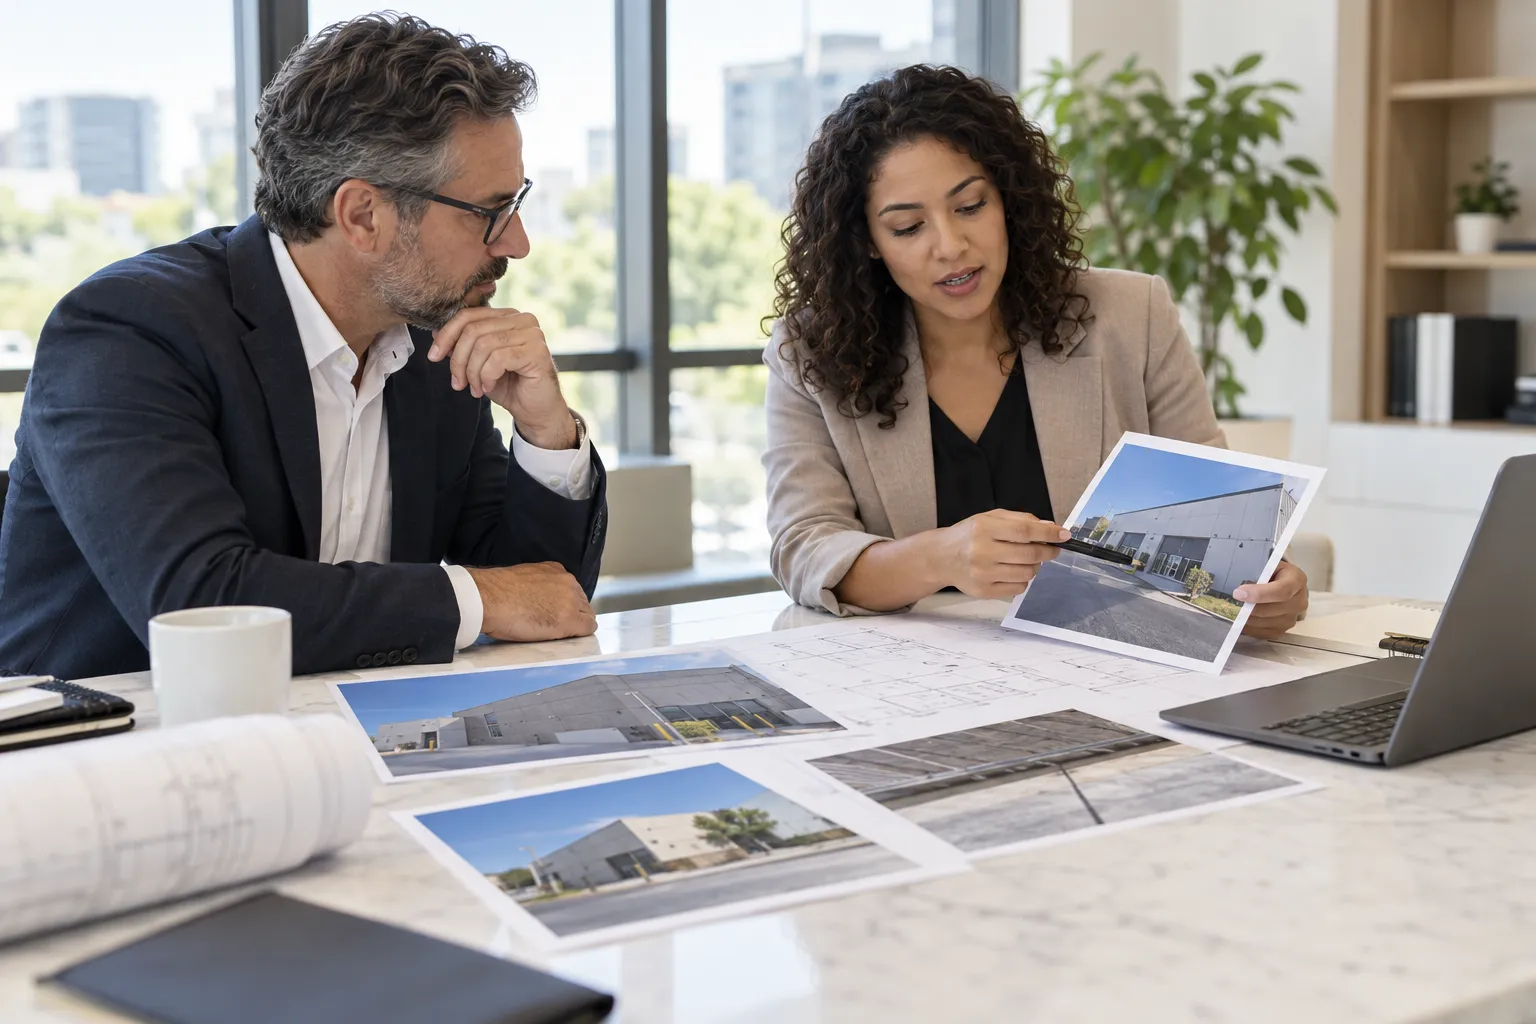
Use the experience to review future coverage

Property owner and adviser reviewing building plans together
  • Revisit the scheduled buildings and insured values.
  • Discuss deductibles and the income protection you need.
  • Use the quote form for future coverage, not a current loss.

After the immediate claim response, review the building schedule, values, deductibles and recovery needs with your agent. The quote form on this page is for prospective insurance, not for reporting or settling an existing claim. Contact your current carrier to report a loss; ask Casurance for help locating the appropriate claims contact.

Build a claim file you can actually use

Policy & claim details
Declarations, claim number and adjuster's contact information.
Damage & repairs
Photographs, estimates, invoices and maintenance records.
Operations & follow-up
Income records, closure dates and a dated correspondence log.

Use the lesson. Review tomorrow's protection.

Review my future coverage

Coverage depends on the policy issued, its terms, limits, deductibles and exclusions. Submitting a request does not bind coverage.

Get a Free Commercial Insurance Quote

Casurance is a licensed commercial insurance agency serving businesses in California, Texas, Nevada, and all 50 states. We work with A-rated carriers to find the right coverage at competitive rates.

Request a Quote Online  ·  Call 1-888-254-0089 — same-day certificates and 24–48 hour quote turnaround.