Casurance

Call: 1-888-254-0089  ·  Mon–Fri 9 am–5 pm PST  ·  Licensed in CA, TX, NV & all 50 states  ·  info@casurance.com

Commercial building with property and liability insurance from Casurance

Commercial Umbrella & Excess Liability Insurance Insurance: Average Premiums & Pricing Factors

Quick Answer

How much does Commercial Umbrella & Excess Liability Insurance cost? Average premiums by business size, industry, and state — plus the key factors that drive y…

Commercial umbrella and excess liability insurance provides additional liability limits above your primary policies — extending protection when underlying general liability, commercial auto, or workers' compensation limits are exhausted by a large claim.

What You Need to Know

Commercial umbrella insurance sits above primary liability policies (GL, commercial auto, employers' liability) and provides additional limits — typically $1M–$25M+ — when a claim exhausts underlying policy limits. It also provides broader coverage ('drops down' to cover some gaps in underlying policies). Excess liability is similar but follows the underlying policy form exactly without broadening coverage. Umbrella/excess is required by many commercial contracts and essential for any business with significant assets or operations that could generate large claims.

Commercial Umbrella & Excess Liability Insurance Cost by Business Size

Business SizeAnnual RevenueTypical PremiumNotes
Small Business / Professional ServicesUnder $5M$500–$2,000/yr ($1M umbrella)Lowest-risk category. Low auto and premises exposure. Often bundled with primary program.
Contractor / Mid-Size Business$5M–$25M$2,000–$8,000/yr ($5M umbrella)Construction, retail, hospitality. Higher liability exposure. Contract requirements often drive limits.
Transportation / Fleet OperationsAny$5,000–$25,000+/yr ($5M umbrella)Trucking, transit, NEMT. Auto liability is primary exposure. High catastrophic loss potential.
Large Commercial / ManufacturingOver $50M$15,000–$100,000+/yr ($10M+ umbrella)Multiple underlying policies. Contract requirements of $25M+ common. Layered program.

What Determines Your Premium?

  • Underlying Policy Types and Limits (High impact) — Umbrella sits above GL, auto, and employers' liability. Higher-risk underlying operations (transportation, construction) produce higher umbrella rates.
  • Umbrella Limit (High impact) — Each $1M of umbrella limit adds cost, but diminishing marginal cost applies — going from $1M to $5M doesn't cost 5x. The first $1M is most expensive; higher layers are cheaper per dollar.
  • Industry and Operations (Very High impact) — Transportation (trucking, transit) companies pay $5,000–$25,000/yr for $5M umbrellas. Construction and manufacturing face similar loads. Professional service firms pay $1,000–$5,000/yr for the same limits.
  • Claims History (High impact) — Large primary GL or auto claims — even those not reaching umbrella limits — signal high-severity exposure and increase umbrella rates.
  • Number of Vehicles (High impact) — Auto liability is a primary source of umbrella claims. Businesses with large vehicle fleets (trucking, NEMT, rideshare) need umbrella programs matched to vehicle exposure.
Choose the layer that fits your primary insurance

A useful premium comparison starts with the same underlying policies, requested limit and attachment point. Share your actual operations and loss history so the review goes beyond a broad price range.

Illustrative commercial district with offices, shops and a delivery van

Price the operation, not just the requested limit

Construction managers reviewing plans on a commercial project

Revenue, payroll, project size, subcontracting and the type of work help underwriters understand severity exposure. Two businesses asking for the same limit can receive different terms and premiums.

  • Describe current and projected operations.
  • List larger contracts and project types.
  • Explain changes since the last renewal.

Separate the impact of the auto exposure

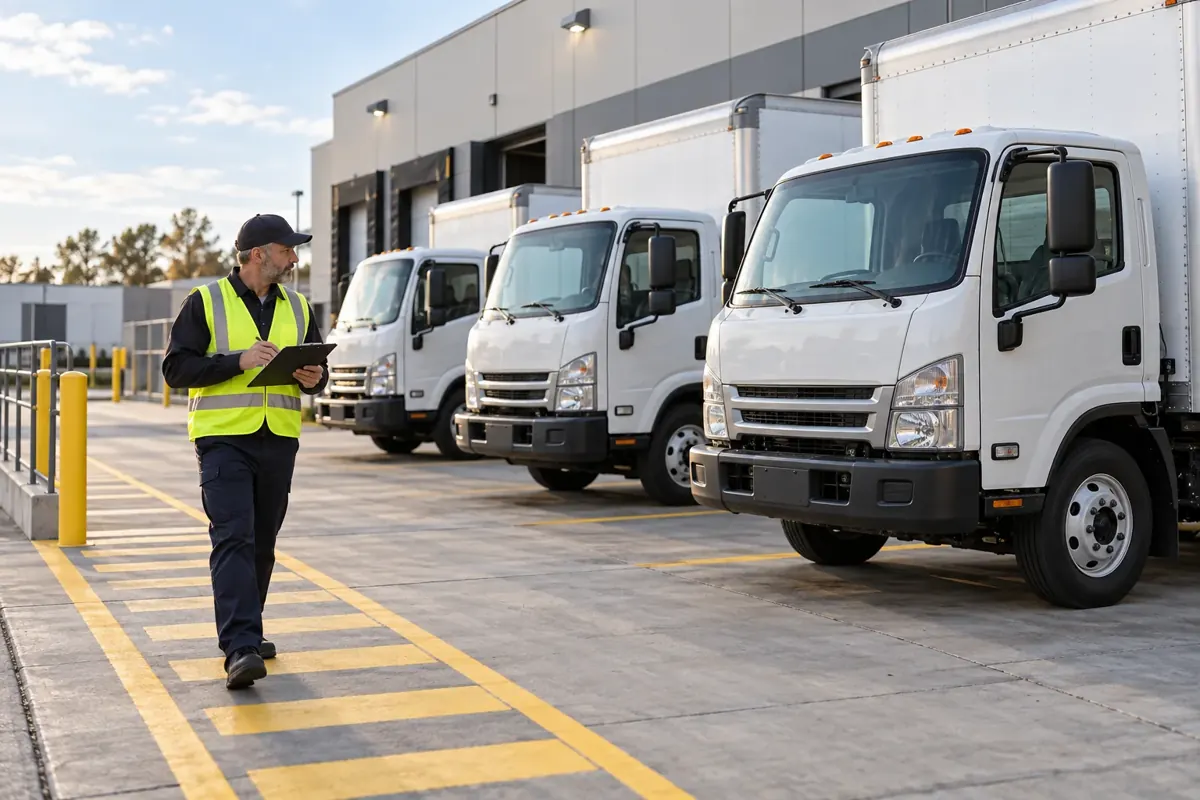
Fleet supervisor inspecting delivery trucks at a depot

Fleet size, vehicle types, radius and passenger or cargo operations can affect how a market views the underlying auto layer. Provide accurate schedules and primary limits when requesting excess auto protection.

  • Identify owned, hired and non-owned exposures.
  • State the underlying auto carrier and limit.
  • Disclose excluded drivers and unusual operations.

Show the full premises schedule

Property managers reviewing pedestrian access in a commercial courtyard

A single office and a multi-location property portfolio present different exposures. Unit counts, occupancy, amenities and the operations of tenants or visitors provide context beyond the mailing address.

  • List all insured entities and locations.
  • Describe pools, parking and public access.
  • Identify contractual limit requirements.

Compare limits, attachment and aggregate together

Manufacturing engineer inspecting a machined component

Premium alone does not show how two quotes differ. A higher attachment point, restrictive endorsement or defense provision can change the protection available even when the headline limit is the same.

  • Align the underlying schedule on every proposal.
  • Compare occurrence and aggregate provisions.
  • Review products and completed-operations terms.

Request a quote supported by actual documents

Business owner and insurance advisor reviewing underlying policies

Published ranges are starting points, not offers of coverage. Current declarations, full policy forms, loss runs and contract requirements help a producer seek terms based on your business.

  • Enter the requested additional limit.
  • Add each underlying policy on Step 2.
  • Upload the documents currently available.

Start your umbrella and excess quote

Carrier availability, attachment requirements and policy terms vary by state and risk.

Get a Free Commercial Insurance Quote

Casurance is a licensed commercial insurance agency serving businesses in California, Texas, Nevada, and all 50 states. We work with A-rated carriers to find the right coverage at competitive rates.

Request a Quote Online  ·  Call 1-888-254-0089 — same-day certificates and 24–48 hour quote turnaround.